The retention metric that could save your mortgage operation thousands
Here’s a stat that surprised many operators when they first hear it: The average cost to replace a loan officer who leaves is around $42,000. That includes recruiting costs, ramp time, lost production
SequifiNovember 25, 2025 3 min read
Here’s a stat that surprised many operators when they first hear it:
The average cost to replace a loan officer who leaves is around $42,000. That includes recruiting costs, ramp time, lost production during transition, and training investment.
If your team loses 2 to 3 producers per year due to commission-related frustration (pay delays, calculation errors, lack of transparency), that adds up to $84,000 to $126,000 in replacement costs alone.
In our work with mortgage operations teams, those who implemented real-time commission visibility using Sequifi saw producer retention improve by an average of 35% year over year. That improvement leads directly to stronger financials: fewer replacement costs, less recruiting spend, and more stable production.
Here's a breakdown of how this impact was measured, why it matters, and how mortgage teams can apply the same model.
Why retention should be a top priority
Turnover among loan officers is a persistent and expensive challenge. For example:- Industry data shows annual turnover rates for mortgage loan officers can average around 32% with an average tenure of about 3.9 years (Polygon Research).
- The cost of replacing a producing loan officer includes recruiting fees, signing bonuses, ramp time, onboarding, and the lost value of client relationships (National Mortgage News).
- From the borrower’s perspective, frequent LO changes can create service gaps, erode trust, and hurt repeat/referral business (Polygon Research).
Modeling the financial impact
By improving retention by 35%, what does that actually mean financially? Example:- A team has 40 producing loan officers.
- Historically, they lose 3 producers per year due to pay-related issues.
- At $42,000 per replacement, that’s $126,000 annually.
- With 35% improvement, the team would retain about one more LO per year.
- Replacement cost drops to $84,000.
- Savings: $42,000 annually.
How mortgage teams measured retention improvements
- Establish a baseline
- Total number of producing loan officers.
- Annual attrition rate of producers.
- Average cost to replace each one.
- Number of compensation disputes, pay delays, or manual override corrections.
- Introduce transparency and automation
- Use Sequifi to give LOs a real-time dashboard showing commission accruals, payout status, and exceptions.
- Automate commission logic to reduce errors.
- Surface any discrepancies clearly so they can be resolved before payout.
- Measure year over year changes
- Compare attrition against the previous year.
- Track reduced hiring/replacement spend.
- Monitor qualitative feedback from loan officers.
- Link to business outcomes
- Lower recruiting costs.
- More consistent production.
- Higher team morale and trust.
- Fewer service disruptions for borrowers.
Why commission visibility drives retention
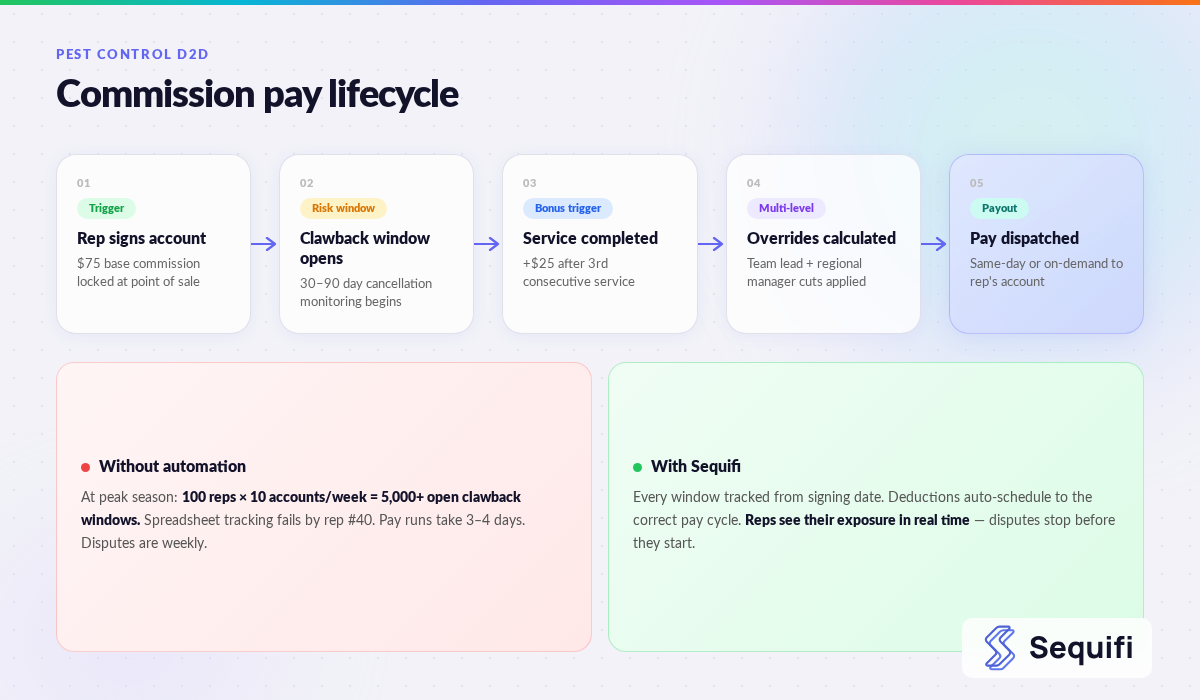
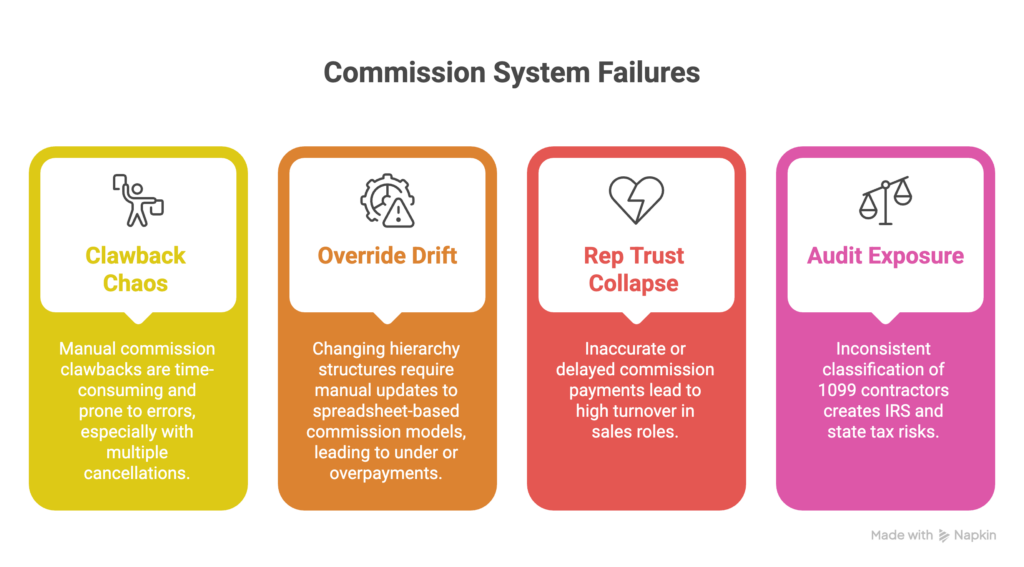
Standard retention programs often miss the mark because they focus on high-level culture or perks rather than day-to-day trust. The most common frustration LOs voice is this: "I don’t know if I’m getting paid correctly or on time." Real-time visibility solves that. Here's how:- Builds trust: LOs can see how their pay is calculated and when to expect it.
- Reduces churn triggers: Errors, clawbacks, and delays drive producers to leave. Visibility prevents that.
- Improves focus: LOs spend more time originating and less time chasing numbers.
- Signals operational strength: Top producers are drawn to companies with modern systems. Clean pay ops signal a serious, growth-ready organization.
Steps to apply this model
- Audit your current attrition and costs
- How many producing LOs did you lose in the past 12 months?
- What was the cost per replacement?
- How many compensation-related disputes or delays occurred?
- Set measurable goals
- Target a 25 to 35% reduction in attrition.
- Model the cost savings from each retained LO.
- Implement visibility and automation
- Deploy real-time dashboards for LO compensation tracking.
- Automate the commission logic to reduce errors and delays.
- Track and communicate improvements
- Compare attrition trends quarterly and annually.
- Share retention wins with the team to reinforce the value of trust-driven operations.
Bottom line
Retention is not just a people problem. It is a profit lever. The cost of losing producing loan officers is too high to ignore, especially when most of the friction comes from outdated compensation workflows. Real-time commission visibility, powered by automation, keeps your producers focused, your pipeline stable, and your recruiting budget under control. If retention is a concern in your mortgage operation, it is time to put your pay process at the center of the conversation.See Sequifi run your kind of pay.
Commissions, payroll and HR in one platform, built for teams where every paycheck is different.
Book a demo